Latest Posts
Inheritance Tax Investigations Hit Six-Year High: Common Mistakes That Could Trigger an HMRC Enquiry and How to Plan
It has recently come to light that HMRC is investigating more inheritance tax returns than it has in six years.
According to recent figures, HMRC opened 4,940 formal inheritance tax enquiries during 2025/26 which amounts to an 18% increase on the previous year. At the same time, nearly 5,000 further estates were referred to HMRC’s compliance team for review before a formal investigation was even opened. This appears to indicate a direction of travel and more resources being applied to collecting IHT.
For executors and beneficiaries (at an already difficult and emotional time) an HMRC enquiry can lead to months of additional administration, requests for extensive documentation, avoidable professional fees and, in some cases, unexpected tax liabilities, interest and penalties.
As advisers, we find that many investigations are triggered by common and avoidable mistakes, often a result of not taking advice at the relevant time. Understanding what HMRC looks for and how to plan effectively for an inheritance tax return can help reduce the risk of an enquiry and ensure an estate is administered as smoothly as possible.
Why are HMRC inheritance tax investigations increasing?
There are many reasons that explain the rise in HMRC enquiries, which we run through in this article.
Among them are frozen inheritance tax thresholds, rising property values over time, cross-border complexities (and ignorance as to these complexities) and increasingly complex family wealth. While these factors become more common, HMRC has also invested significantly in compliance and is placing greater emphasis on identifying inaccurate or incomplete returns.
It is important to add, however, that a higher number of investigations does not necessarily mean more people are deliberately avoiding tax. In fact, many enquiries arise because HMRC requires further information before it is satisfied that an estate has been valued correctly. As mentioned above and throughout this article, the stress and work triggered by such an enquiry (even where tax has been paid accurately) can be prevented in the first place.
Undervaluing property in an inheritance tax return
One of the most common reasons for an inheritance tax enquiry is the valuation of residential or investment property, which is often and understandably the most valuable asset in an individual’s estate.
HMRC regularly reviews valuations where:
- properties appear significantly below local market values;
- no professional valuation has been obtained;
- development potential has not been considered; or
- comparable sales suggest a higher value.
Obtaining an independent valuation from an appropriately qualified surveyor can significantly reduce the likelihood of questions being raised later.
Failure to declare lifetime gifts to HMRC
Even for those who are not tax advisers like us, the “seven-year rule” will sound familiar and be broadly understood.
Lifetime gifts may still need to be disclosed even where no inheritance tax is ultimately payable. HMRC frequently examines:
- large transfers of cash;
- gifts of property;
- transfers into trust; and
- gifts made shortly before death.
Executors should ensure they have a complete picture of any lifetime gifting before submitting an inheritance tax return, but this can be aided by individuals keeping records of such gifts during their lifetime.
Gifts where the donor continued to benefit from the asset
Although the seven-year rule is often mentioned, the gift with reservation of benefit rules are generally not understood.
For example, if someone transfers their home to a child but continues living there without paying a full market rent, HMRC may still treat the property as remaining within their estate for inheritance tax purposes. This is despite the fact that the parents, in this scenario, think they have effectively carried out inheritance tax planning.
These arrangements are a common focus of HMRC enquiries and they underscore the need for professional advice when considering lifetime gifts to mitigate inheritance tax.
Missing assets from the inheritance tax return
HMRC has increasing access to financial information from a range of sources.
Bank accounts, investments, shareholdings, overseas assets and business interests should all be identified and accurately reported. Even unintentional omissions can result in delays while HMRC requests further information. This is increasingly the case with assets such as crypto assets. Again, this highlights the need for executors to put in place not simply a Will but to also record accurately details of their assets and provide access to them at the relevant time. In other words, the contents of the safe are immaterial without the keys to access them.
Incorrect Business Property Relief or Agricultural Property Relief claims
Business Property Relief (BPR) and Agricultural Property Relief (APR) can provide valuable inheritance tax savings, but they are also subject to detailed conditions and come with their complexity, particularly given the reforms to these reliefs in recent years. In a nutshell, complacency and assumptions rarely work when it comes to tax planning and that is certainly the case with APR and BPR.
HMRC will often examine:
- whether a business/ farmland genuinely qualifies;
- whether investment activities outweighed trading activities;
- ownership periods; and
- the nature of the assets involved.
Specialist advice is particularly important where reliefs are being claimed.
Inconsistent information across probate documents and inheritance tax documents
The information submitted to HMRC should align with probate applications and supporting documentation.
Differences between property values, asset schedules or financial information can prompt HMRC to ask further questions, even where the discrepancy is simply an administrative error.
Careful preparation before submission can avoid unnecessary delays.
Poor record keeping by executors
Executors are responsible for demonstrating how estate values have been calculated.
HMRC may request:
- property valuations;
- bank statements;
- investment schedules;
- gift records;
- trust documentation;
- correspondence; and
- supporting calculations.
The better the records, the easier it is to respond to any enquiry.
Failing to disclose overseas assets
International families often have assets in multiple jurisdictions.
Foreign property, offshore bank accounts, overseas investments and non-UK trusts can all create additional reporting requirements and significant complexity.
Failure to disclose overseas assets accurately is an area that receives increasing scrutiny from HMRC.
In addition, we often find Wills to be inadequate to cover the relevant jurisdictions and specialist advice is crucial to overcome these cross-border issues.
Complex family arrangements
Modern families are often more complex than first anticipated.
Second marriages, blended families, family companies, trusts and jointly owned assets can all affect inheritance tax outcomes.
Seeking advice before submitting returns can help avoid costly mistakes later.
Leaving inheritance tax planning until it’s too late
Perhaps the biggest mistake is assuming inheritance tax planning only becomes relevant after someone has died or when old age kicks in (at which point it can be too late).
Effective lifetime planning can include:
- making use of available gift exemptions;
- reviewing wills regularly;
- considering trusts where appropriate;
- ensuring assets are correctly owned; and
- reviewing eligibility for available inheritance tax reliefs.
Planning early can not only reduce inheritance tax but also make the administration of an estate significantly easier for executors and beneficiaries.
What should executors do if HMRC opens an enquiry?
Receiving an HMRC enquiry does not necessarily mean anything has been done wrong.
Many enquiries simply involve requests for additional information or clarification. However, responding promptly, accurately and with appropriate professional advice can help resolve matters more efficiently.
Executors should avoid making assumptions, ensure all supporting evidence is retained and seek legal advice where valuations, gifts or relief claims may be challenged.
How can you reduce the risk of an inheritance tax investigation?
Although scrutiny cannot be entirely prevented, there are several practical steps that can reduce the likelihood of an HMRC enquiry:
- Obtain professional valuations for significant assets.
- Keep detailed records of lifetime gifts.
- Review inheritance tax planning regularly rather than leaving it until later life.
- Ensure all assets and liabilities are disclosed accurately.
- Take specialist advice where trusts, businesses, agricultural assets or overseas property are involved.
How Quastels can help
Inheritance tax investigations are becoming more common, but careful planning and expert advice can make a significant difference.
Whether you are planning your estate, acting as an executor or responding to an HMRC enquiry, obtaining specialist advice at an early stage can help minimise delays, reduce uncertainty and ensure that the estate is administered correctly.
Quastels’ Private Wealth team advises individuals, families, executors and trustees on all aspects of inheritance tax planning, estate administration, wills, trusts and HMRC enquiries. If you would like advice tailored to your circumstances, please get in touch with our team to discuss how we can help.
Read More
Buried Treasure? HMRC Is Hunting for Hidden Cryptoassets
Following recent developments, HMRC will soon have access to information on many cryptoasset holdings, and is taking the opportunity to issue a reminder that these need to be reported as part of taxable estates.
A letter from HMRC
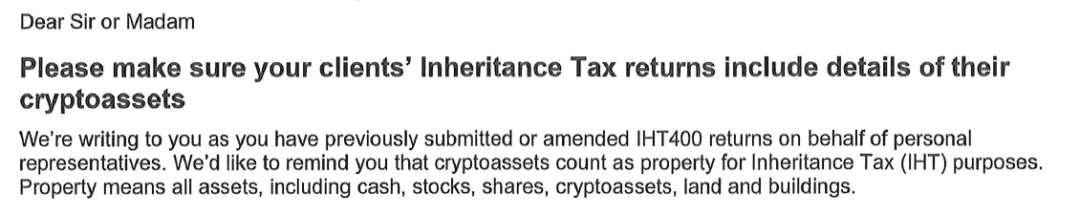
HMRC recently sent a letter to professionals who have previously submitted Inheritance Tax returns, reminding them that cryptoassets are subject to Inheritance Tax (IHT). The letter instructs recipients to check whether estates include cryptoassets, and to make sure they are reported to HMRC as part of a return. Where submitted returns have failed to mention a cryptoasset belonging to the deceased, HMRC point out that this must be amended.
When are cryptoassets subject to IHT?
Under the rules that apply to deaths since 6 April 2025, IHT is charged on all assets of a person who dies as a Long Term Resident of the UK, which means they have spent at least 10 of the last 20 years as a UK tax resident. (A year of residence for these purposes is determined by the UK’s Statutory Residence Test.) Those who are not Long Term Residents will only be subject to IHT on their assets located in the UK.
Of course, this rule is not so straightforward to apply to decentralised cryptoassets, which can’t really be said to have a ‘location’ in any meaningful sense. There are various different arguments that can be made for how their legal location can be identified in English law. HMRC have advanced their own theory (albeit one without much legal basis or support from professionals or academics) that this is based on the residence of the beneficial owner of the cryptoasset.
This can lead to some surprising results. Imagine an Italian with cryptoassets held by a Swiss custodian, who decides to spend a few years in the UK. She has been advised that her foreign assets are not subject to IHT until she has spent at least 10 years in the UK, and so assumes that her cryptoassets are currently exempt from IHT. However, if she dies two years after arriving in the UK, HMRC would take the view that because she was UK resident, the cryptoassets are UK assets, and therefore subject to IHT. Of course, had she been properly advised, our Italian cryptoholder would ideally have undertaken pre-arrival planning to mitigate this potential exposure to IHT.
The CARF
At first glance, it is not obvious what has prompted this reminder from HMRC, since the law on this point has not changed. As HMRC point out, while there is no specific reference to cryptoassets in IHT legislation, the wording in the Inheritance Tax Act 1985 is certainly broad enough to apply to cryptoassets.
Perhaps the reason for this letter is the introduction at the start of this year of the Crypto-Asset Reporting Framework (CARF) in many jurisdictions, including the UK. The CARF is an international agreement for information sharing, similar in some ways to the Common Reporting Standard (CRS). The idea behind the CARF is that cryptoasset service providers (such as exchanges, for example) will be obliged to identify their customers and collect certain information about their activities (for example, sales and purchases of cryptoassets) so that this can be shared with the tax authorities wherever the customer is resident.
This additional transparency may bring unwelcome surprises for those who have either assumed that they did not have to pay tax on cryptoassets, or believed HMRC would never find out. If the CARF data suggests a person had been selling cryptoassets at a gain, and they failed to report that gain to HMRC, it is likely that HMRC will have further questions. Similarly, if HMRC knows from CARF that a person was investing in cryptoassets, and their personal representatives submit an IHT account that fails to disclose these, we expect that HMRC will get in touch.
Difficulties identifying cryptoassets
Of course, it’s one thing to know that cryptoassets need to be declared for IHT purposes, and quite another for personal representatives to know whether a deceased person owned them, or indeed find out the quantities and types of token that were owned. If the deceased did not leave accessible records, it may be difficult if not impossible to identify their cryptoassets. It’s easy to imagine that in many cases, a CARF-prompted enquiry from HMRC might be the first clue many personal representatives may have that there are cryptoassets in an estate.
Even where a deceased’s cryptoassets can be identified, that does not mean that personal representatives will be able to realise their value. For cryptoassets held in the deceased’s own custody (rather than, for example, held by an exchange or other custodian), the personal representatives will not be able to make a sale or transfer unless they can discover the private keys. This does lead to the possibility of a worst-case scenario where the personal representatives and HMRC know that there are cryptoassets in the estate, and HMRC are asking for tax, but the assets cannot be sold to pay it.
What should you do?
This illustrates well the importance of succession planning for those with cryptoassets. A Will by itself is not enough; you also need to ensure you have a system in place for your personal representatives to be able to identify your assets and also access the necessary private keys. This is a complex topic, and there are a variety of different solutions that might be appropriate in different circumstances, but the Private Wealth and Tax team at Quastels is well-qualified to be able to advise.
Read More
Business Property Relief – Last Call Before the Cap
The changes to Business Property Relief (BPR) that come into force on 6 April 2026 are fast approaching. There is however still time to mitigate your exposure to IHT and the potential impact of the new regime.
For a full summary of the changes coming into effect, please see our previous article here. By way of brief summary, the changes will mean that from 6 April 2026 a cap will be introduced on the total value of property on which BPR can be claimed at a rate of 100%. The subsequent changes announced on 23 December 2025, mean that the 100% relief will be available on up to £2.5million of qualifying business assets and anything above this will be limited to a 50% relief.
The introduction of this threshold is likely to result in more individuals having a sizeable IHT bill on their passing. There is, however, still time to utilise the current regime related to BPR before the 6 April 2026, and this could include making lifetime gifts of company shares or redirecting those assets into a trust.
Let us consider an example of gifting assets to a trust:
An individual currently holds unquoted shares valued at £8,000,000 in their personal name. The unquoted shares have been held by the individual for over two years and meet the requirements and therefore would qualify for BPR at a rate of 100%.
The gift to the trust is made before 6 April 2026:
If the individual was to set up a trust (for the benefit of their children, for example) and make a gift of the total value of the unquoted shares which qualify for BPR before 6 April 2026 into this trust, the value chargeable to IHT on the entry of the assets into the trust would be zero as the gift qualifies for BPR in full. The individual would have therefore made a gift removing the assets from their estate without any immediate IHT charge.
The gift to the trust is made after 6 April 2026:
If, however, the same individual was to make a gift into the trust after 6 April 2026, only the first £2,500,000 would qualify for relief at the 100% rate. The remaining £5,500,000 would benefit from relief at a rate of 50%, leaving £2,750,000. After deducting the Nil Rate Band of £325,000, this leaves £2,425,000 which is subject to a lifetime IHT rate of 20%, meaning that the IHT payable upon putting these assets into trust is £485,000. In effect, this will be 10% of the value of the transfer in excess of £3,150,000 (assuming the Nil Rate Band is available in full).
Tax on Death
In either case, if the individual dies within seven years of the transfer, the gift would potentially be subject to tax upon death at the full 40% rate of IHT. If that death takes place from 6 April 2026, the new restrictions on BPR will apply, even if the gift was made before that date.
What Should I Do?
At the time of publication, there is still just about time to explore the options to mitigate your exposure to IHT in relation to your qualifying business assets. Whilst making a gift to a trust for example could result in no immediate IHT implications, anyone looking to make those gifts should be aware of the potential implications if they were to die within seven years of making this gift as well as the ongoing tax liability in relation to the assets being held within the trust. Further planning to consider therefore could be term life insurance policies which could pay out to cover the IHT due in the event of death within seven years. Alternatively, whole of life policies could be used to provide a payment on death to cover the IHT due on a business. When creating trusts, it is also worth considering whether it is possible to split the gift with a spouse or civil partner, in order to make the most of both parties’ allowances.
If you are planning to utilise BPR as part of your succession plan before the changes on 6 April 2026, please do contact the Private Wealth and Tax team at Quastels.
Read More